
Market and Asset Allocation Update – October 2026
CiN-sights Asset Allocation - October 2026
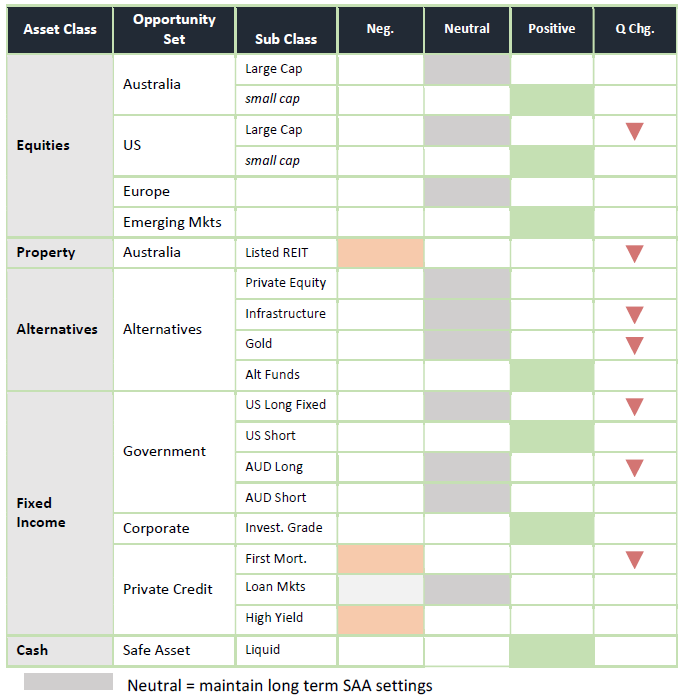
Dynamic Asset Allocation Calls (Quarterly view)
To make money in this world, you have to be the first son, second wife or third developer – Al “Chainsaw” Dunlap
Australian Equities: Currently hard to get bullish on the domestic market and unsurprising that asset allocators are diverting funds elsewhere. In general, Corporate Australia is in good shape but not matched in this way by the underlying low productivity Australian economy. We are underweight Banks and financials, overweight Commodities and selective buyers in the Industrial sector. We see the market providing an “average” return in the short term. Small Caps have some attraction and is where we will focus attention.
US Equities: Valuations based on future earnings are priced for perfection. Watchful - yes, but momentum keeps us sitting at the table. At this point, the question that investors could be asking themselves: Why is it that equity markets are not falling more on negative news? Conversely, what happens if all these negatives peak or even turn around? To that end, we remain constructive with seasonality supporting (hello Santa). The mid-terms to not be impactful. Rising bond yields will have gravitational force at some point. Not yet.
European Equities: Sticky inflation, higher energy costs and higher bond yields are the drag here. However, these are offset by cheap valuations and good earnings. Again, the proverbial mixed bag. We have attraction to the Bank and Financials, Energy, Healthcare and Industrial sectors. Hold at LT SAA settings.
Emerging Markets: Despite kinetic and tariff wars, the overall EM cohort has held up well. Global Capex E spend for AI has benefitted Taiwan and S Korea resulting in volatile markets. India looks to be on the rebound and economically China is currently challenged, but the MAG7 equivalent is underpriced and there is always a stimulus around the corner. Preference is for the broader (IEM) over the ex-China (EMXC) etf.
Property: Rising rates, AI and a flattening economic outlook are the reasons to be underweight here. Some good yields available will see sporadic buying but given uncertainty on terminal cap rates, sell into rallies.
Private Equity: Buy straw hats in winter? Will this be a great vintage to invest in? Pick your manager and specialty and assess the returns vs illiquidity. Otherwise stay in broad and diversified semi-liquid structures.
Infrastructure: Rising rates causes revaluation discounts on cash flows and future values. We temper our enthusiasm but continue to allocate at longer term settings. When the bond market turns, we will upweight.
Gold: We remain a bull over the long term but recognise the short-term headwinds that will crimp sentiment; higher US interest rates and a strong US $ being the two major factors. Hold LT settings. Neutral.
Fixed Interest: Global yields have backed off due to 1.Resilient Growth 2. Sticky Inflation 3. Heavy Issuance 4. Fiscal concerns and 5. Reinstatement of a term risk premia. So, we like the yields being presented to us, but do not like capital losses and the momentum in the current market. Therefore, we put our hands back in our pockets, except for the US short bond market where we get good yield with limited duration We do like Australian Corporate Bonds for yield and margin, so happy to deploy to the 7%+ yields on offer. Long Bonds? - tempted to lean in, maybe soon.
Private Credit: Not short of headlines here. Longer Term the negativity is good for the asset class in tightening all aspects of operations, risk and returns. In the short term, there will be opportunities caused by “horror” headlines and price/liquidity mismatches. We maintain a healthy scepticism and pick quality stories. Focus is away from Corporate Real Estate and the interest rate sensitive High Yield sectors.
Cash: Overweight. We now see attractive yields with money market etfs above 5 and TDs in the mid to high 5’s. Cash continues to give us “optionality” and recent rate rises have been a reward for patience.
DAA Calls enclosed proposed are for general investment purposes. Please discuss with Carnbrea the suitability of any recommendation to portfolios and the context of client SAA construct, holdings, return analysis and tax consideration. This document has been prepared and issued by Carnbrea & Co Limited ABN 33 004 739 655 (‘Carnbrea’), Australian Financial Services Licence No 233763. Any advice included in this document is general in nature and does not consider your objectives, financial situation or needs. Before acting on the advice, you should consider whether it’s appropriate to you. If a product we recommend has a Product Disclosure Statement (PDS), you should read it before making a decision. Past performance is not a reliable indicator of future performance. Derivatives are leveraged products which means gains and losses are magnified, and you may lose substantially more than your initial investment. We do not endorse any information from research providers that we provide to you unless we specifically say so.
Copyright © | 2026 |Carnbrea & Co.| All rights reserved